


Sponsors of California’s Billionaire Tax Act are collecting signatures for a ballot proposition that would impose a 5 percent wealth tax on billionaires, billed as a one-time levy. The unions backing the initiative claim it will raise $100 billion in revenue.
Last month, we published “The Net Present Value of the Billionaire Tax Act,” a person-by-person fiscal analysis of the proposal. We estimated that the tax would raise approximately $40 billion, less than half the amount projected by its proponents, and that the present value of permanently lost income tax revenue from departing billionaires would more than offset even that reduced figure.
The proponents have made several statements in response. One of the initiative’s architects denounced our analysis as “dishonest” on X and “bad faith” in the Sacramento Bee.
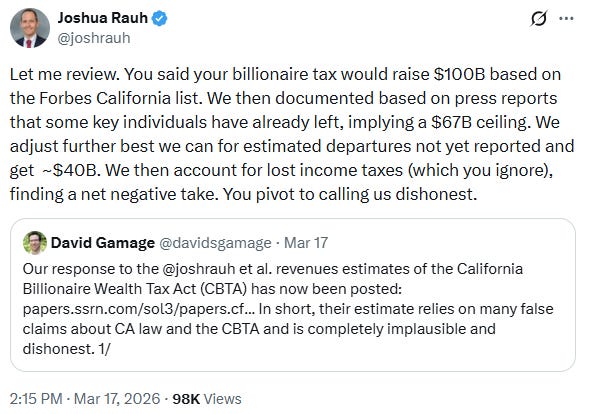
This piece examines the source of the disagreement, explains why the proponents’ central defense of the tax is wrong and why that error undermines their revenue projections, and shows that our estimates are accurate and made in good faith
The Tax Is Not One-Time in Expectation
The proponents’ central defense of the Billionaire Tax Act is that it imposes a one-time levy. Because the tax is collected once, they argue, billionaires have no reason to leave. This argument misunderstands how constitutional constraints shape taxpayer behavior.
California’s constitution currently caps taxes on intangible personal property at 0.4 percent per year. That cap has functioned for decades as a binding commitment to every taxpayer in the state: California could decide to tax your financial wealth, but there is a limit on the annual rate.1 That cap has been the institutional reason a high-net-worth individual could hold equity in a California-headquartered company, knowing that there were limits to state-level wealth taxation.
In the framework of constitutional economics developed by Buchanan and Tullock (1962), such rules exist precisely to constrain future political decision-makers. They bind the hands of future majorities so that individuals can make long-horizon investment and residency decisions with confidence that the rules will not change after the fact. The key insight is that a constitutional cap on wealth taxation is valuable not for what it prohibits today but for what it credibly prohibits tomorrow.
The Billionaire Tax Act proposes to amend the state constitution to override this cap. There is debate over whether this cap formally reinstates after the one-time levy, but that is secondary to the larger question: what does the Billionaire Tax Act reveal about the state’s willingness to use constitutional amendments as instruments of wealth taxation? If California voters lift the cap once, they have demonstrated that the cap can be lifted again.
A constitutional provision that proves to be one that voters will amend whenever it becomes politically convenient is no longer a constraint. It is a suggestion.
This is not a hypothetical concern. California has a documented history of enacting “temporary” tax measures and extending them. Proposition 30, passed in 2012, raised marginal income tax rates on top earners significantly and was sold to voters as “temporary taxes to fund education” expiring in 2018. Before it expired, voters passed Proposition 55, extending those rates through 2030. The state’s track record converts “one-time” from a legal description into a political aspiration.
The correct way to evaluate the Billionaire Tax Act is therefore not to ask whether the statute says “one-time.” It is to ask what a rational taxpayer would forecast about California’s future tax regime after the amendment passes. That forecast must incorporate the probability that voters, having lifted the constitutional cap once to tax billionaires at 5 percent, will do so again at the same or higher rate, potentially at lower wealth thresholds.2 The expected tax burden on remaining in California is not 5 percent of wealth paid once. It is 5 percent plus the discounted expected value of every future wealth tax this amendment makes politically feasible.
Billionaires and their advisors have performed this exact calculation. Their departures do not reflect a reaction of a single payment they cannot avoid, but a response more akin to expectation of a permanent shift in the state’s institutional credibility. The constitutional cap coupled with no enactment or serious suggestion of a wealth tax was the commitment device. The Billionaire Tax Act breaks it.
Legal Incidence Does Not Determine Behavioral Response
This commitment problem exposes a deeper error in the proponents’ reasoning. Their revenue model treats the legal characterization of the tax as determinative of the behavioral response it produces. Because the statute says “one-time,” they assume taxpayers will treat the payment as a surprise lump sum that does not alter future residency decisions. The assumed avoidance rate of 10 percent reflects this premise.
The premise is wrong as a matter of economics. What determines behavioral response is not legal incidence but taxpayer expectations about the jurisdiction’s future tax regime. A lump-sum tax generates no behavioral distortion only if it is truly unanticipated and if taxpayers believe it will never recur. Neither condition holds here. Since the initiative was filed publicly, billionaires had some advance notice. And as described above, the constitutional amendment creates permanent infrastructure for future wealth taxation that any rational advisor would price into a residency decision.
The observed data confirm this. Six billionaires representing 28.3 percent of the wealth tax base departed California between the initiative’s filing and the January 1, 2026 residency snapshot date. When four additional founders who departed or announced plans to depart after the snapshot are included, the figure rises to about 40 percent.
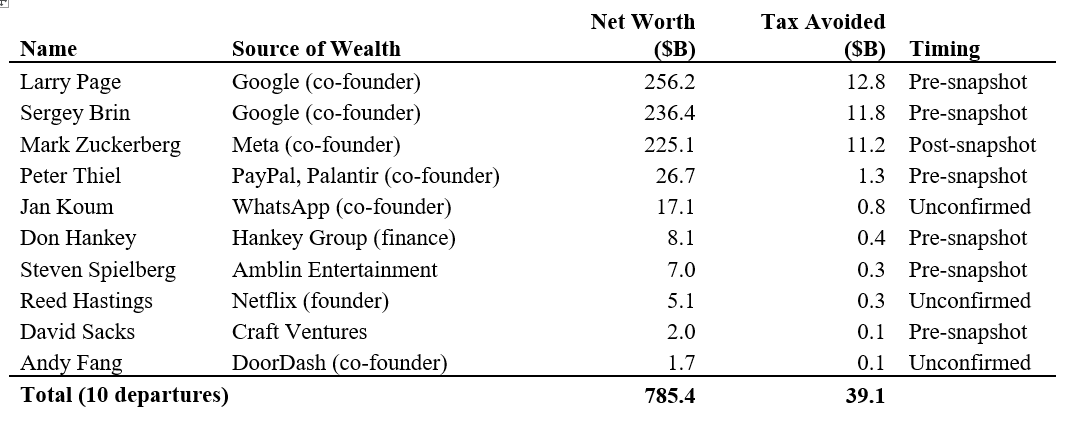
These are observed responses to the actual California tax proposal, not parameters imported from European studies. The proponents assumed 10 percent avoidance. The confirmed departures alone tripled that figure before signatures were collected.
These departures are the market test of the proponents’ theory. If billionaires believed this was a painless one-time payment with no implications for the future, many more would stay and pay. They did not stay. Instead, they left, revealing that they expect repetition regardless of statutory language.
The Independent Reviewer and the Arithmetic
Now to address the claim that our estimates were done in “bad faith.” At Gamage’s urging, Professor Jeff Hoopes of the University of North Carolina reviewed both our paper and the proponents’ report, of which Gamage is a lead author.3 Hoopes concluded that the proponents used a simpler methodology while our team went further into the details of each billionaire’s situation. For example, the proponents did not exclude residential real estate from the tax base or verify individual residency, despite the initiative’s own text requiring both adjustments. Hoopes agreed with our finding that the tax would encourage billionaires to leave. An analysis validated by an independent reviewer selected by one’s critic is not bad faith.
Set aside behavioral estimates entirely. Even assuming zero unobserved departures beyond the six confirmed, the corrected revenue ceiling is $67.5 billion, not $100 billion. That figure follows directly from the observed contraction in the tax base. Before the proposal, there was only $94 billion of potentially taxable billionaire wealth, after Larry Ellison’s 2020 move to Hawaii, which predates the proposal. By the December 31 cutoff, that base had fallen to $67.5 billion. The proponents’ headline estimate nonetheless includes Ellison, applies the 5 percent rate to residential real estate that the initiative’s own text exempts, and assumes only 10 percent avoidance when confirmed departures alone imply at least a 28 percent reduction in the base. These are not disputes over behavioral parameters. They are errors of fact and statute.
The assumption Gamage seems to take issue with is how we used the wealth tax migration literature to infer what that $67.5 billion will fall to when all is said and done, meaning when we find out exactly who succeeded in severing California residency. It is implausible that the only departures among the 212 billionaires are the six reported in the press, implying a larger unobserved effect.
For example, among the six billionaires we counted as having already departed, we did not include Mark Zuckerberg, who established residence in Florida early 2026. If he succeeds in court at challenging the state’s wealth tax claim on him, that would be an additional $10-11 billion off the wealth tax take right there.
Our analysis simulates the net present value of the wealth tax across a range of revenue assumptions, from $35 billion to an upper bound of $67.5 billion. The upper bound is itself extraordinarily conservative: it assumes the full statutory revenue is collected with no avoidance, no valuation disputes, and no administrative losses. We also vary income tax collections and discount rates, running over 100,000 simulations. In 71 percent of cases, the net present value for the state is negative.
These are based on different calibrations from the literature. The primary evidence on wealth tax migration we used was from Brülhart et al. (2022), published in the American Economic Journal: Economic Policy, which documents large migration responses to cantonal wealth taxes in Switzerland. They find that per percentage point change in the wealth tax at the cantonal level, taxable wealth fell by 10% due to departures. The question is what wealth tax the California billionaires were responding to – a one percentage point change in a wealth tax in Swiss cantons that could be quickly reversed versus a five percent California wealth tax billed as “one-time” but with everyone believing it could be repeated. Plus moving between US states is arguably significantly less costly than moving between Swiss cantons, given language differences and the fact that Swiss government as measured by expenditures is roughly 2/3rds cantonal and 1/3rd federal, the flip of the U.S. where it is approximately 2/3rds federal and 1/3rd state.
Our paper presents sensitivity analysis with respect to this initial wealth tax take. Gamage/Saez seem to have recently begun to argue that their 5% one-time tax is actually equivalent to a 1% tax each year for 5 years as a defense of their 10% number. However, the fact that already 28% of the tax base is gone without our yet being able to see the full picture makes it clear that their 10% was not a good assumption.
In the end, the question is not what the statute says, but what taxpayers believe—and on that question, California’s billionaires have already rendered their verdict.
Mr. Rauh is the George P. Shultz Senior Fellow in economics at the Hoover Institution and a finance professor at the Stanford Graduate School of Business. Mr. Jaros is a research fellow at the Hoover Institution.
California taxed intangible personal property at rates above 0.4% from statehood through the 1930s. The Legislature exempted most intangibles in 1935. Voters adopted the 0.4% constitutional cap in 1974 via Proposition 8, making it a precautionary ceiling limiting taxing power that had been dormant for nearly four decades.
This is not hypothetical. In March 2026, polling was conducted testing support for a California wealth tax at a $10 million threshold. See @Nowooski, X, March 29, 2026,


See Ben Paviour, ‘Will California’s Billionaire Tax Pay Off? New Studies Sharply Disagree,’ Sacramento Bee, March 25, 2026, https://www.swoknews.com/ap/national/will-california-s-billionaire-tax-pay-off-new-studies-sharply-disagree/article_a7fde862-a343-545c-9c10-b9c57a12db27.html.”

As a life-long conservative and Californian, I want the tax to pass. It has the power to weaken California and make it an example to the rest of the country.
California will already lose House Representatives in the 2030 census (great!) and a wealth tax could help Republicans keep the presidency in 2028.
Being a bit more skeptical, I would ask who in their right mind would stay? I'm less interested in sensitivity analysis around absurd input assumptions.